The Scale of the Problem Is Bigger Than You’d Think
Nearly a quarter of consumers said they did not redeem card rewards they had coming to them in the past year, though the majority said they were simply waiting for a specific opportunity to use them. The intent is there, but the follow-through often isn’t.
At the end of 2022, the average rewards credit card account had an average of $192 in unspent rewards sitting idle. Multiply that across millions of cardholders and the number becomes genuinely eye-opening.
Reward-related consumer complaints rose 71% in 2023 compared to pre-pandemic years, a sign that frustration is growing even as redemption habits remain slow to change. People know something is being left on the table. They just aren’t sure what to do about it.
The Hidden Insurance Nobody Reads About
According to WalletHub research, there is a significant information gap between credit card issuers and users when it comes to lesser-known benefits like rental car coverage, travel insurance, and cell phone insurance, which leads to widespread underuse.
Complex policy language, skepticism about reliability, and overlap with other insurance contribute to this disconnect, and these are barriers that often prevent consumers from taking full advantage of their credit card benefits.
Many of the best credit cards on the market today offer built-in insurance protections, including travel insurance that covers trip cancellations and interruptions, extended warranties, and purchase protection against damage or theft. Most cardholders simply don’t know these protections exist until they need them and it’s already too late.
Cell Phone Protection: The Perk People Keep Paying to Ignore
Credit card cell phone insurance is a major benefit offered by some cards and is relatively easy to use, though not all cards offer this coverage, and those that do have important fine print and limitations worth knowing.
Credit card cell phone protection works exactly as it sounds: if something bad happens to your phone, and your situation falls within the guidelines the card issuer sets out, your card’s insurance will help cover the cost of getting it fixed or replaced. The typical requirement is simply that you pay your monthly phone bill with that card.
Some cards cover up to $600 in cell phone protection against damage or theft with only a modest $25 deductible, as long as you use the card to pay your monthly bill. Meanwhile, third-party phone insurance plans from carriers routinely cost $15 or more per month. The math is obvious once you see it.
Purchase Protection and Extended Warranty Benefits
Credit cards come with lots of bells and whistles, and some of the lesser-known benefits include protections that come complimentary for eligible purchases made with the card. Purchase protection typically covers theft or accidental damage on recent purchases for a set window of time.
Some cards offer return protection, meaning that if you try to return an eligible item within 90 days of purchase and the merchant declines, you can get a full refund up to $300 per item and $1,000 annually. That’s a rare perk typically available only with premium credit cards.
Extended warranty coverage is equally overlooked. Many cards automatically extend the manufacturer’s warranty on eligible purchases, sometimes by an additional year. For electronics or appliances, that’s real value that most people purchase separately without ever checking if they already have it.
Travel Delay and Trip Cancellation Coverage
Nearly one in four flights, about 22.5%, were delayed in the first half of 2025, according to data from the U.S. Bureau of Transportation Statistics. That figure alone makes travel insurance worth understanding before your next trip.
Credit card issuers are increasingly focused on travel as a selling point, and some issuers even have their own travel portals that incentivize booking through their website or app. Trip delay coverage, which reimburses cardholders for meals and accommodation when delays exceed a threshold, is one of the most consistently underused perks of all.
Cards like the Ink Business Preferred cover cardholders for purchase protection, extended warranty protection, primary car rental coverage, and trip cancellation and trip interruption insurance all in one package. For travelers who rely on their cards anyway, activating this coverage costs nothing extra.
Airport Lounge Access: Not Just for Elite Travelers
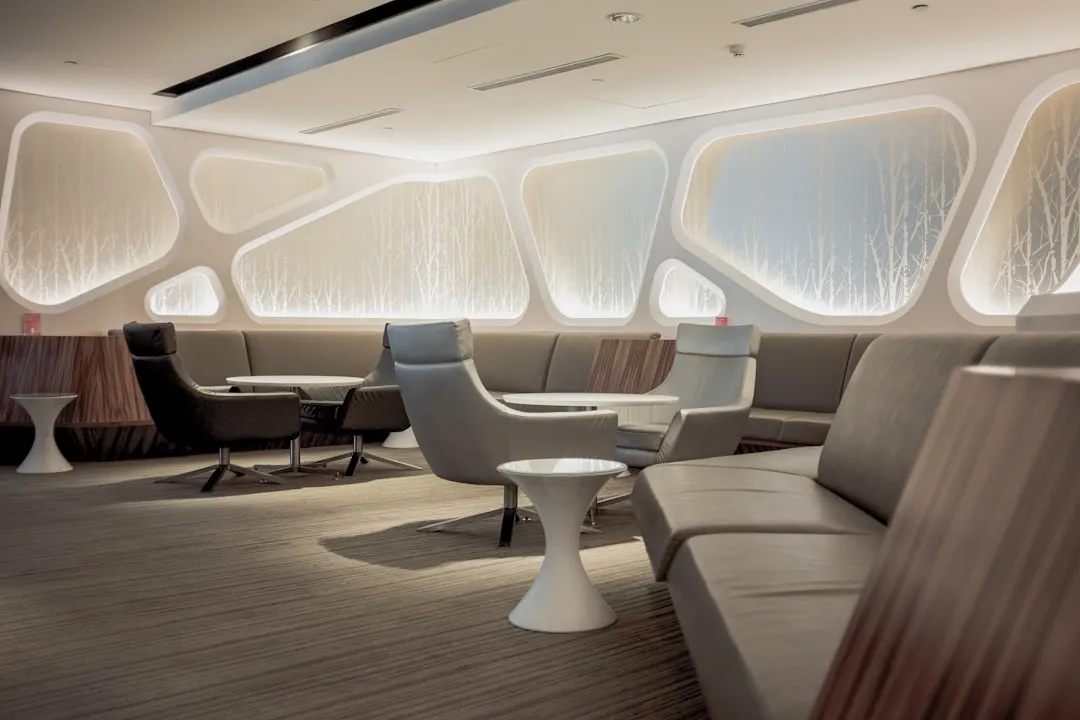
American Express now boasts over 40 lounges around the world, with additional locations opening in Washington D.C., Atlanta, and Newark. Access to lounges was once viewed as a luxury reserved for frequent business flyers. That perception is changing.
Card rewards programs now have branded airport lounges for cardholders, and access is often tied to holding a specific card rather than any flight status. Yet millions of eligible cardholders still pay out of pocket for food and drinks at airports when they could walk straight into a complimentary lounge.
According to Forbes Research’s 2025 Mass Affluent Survey, concierge access is now one of the least-valued features among affluent cardholders, with just 9% citing it as most valued, down sharply from 40% in 2024. Tastes are shifting, but lounge access remains one of the clearest value-for-money perks available to mid-tier cardholders.
Dining Credits That Quietly Expire Each Month
The American Express Gold Card gives cardholders a $120 dining bonus per year by crediting $10 per month toward Grubhub, The Cheesecake Factory, Goldbelly, Wine.com, Milk Bar, and Shake Shack orders. That credit resets monthly. Miss it once and it’s gone.
The problem with monthly credits, whether for dining, streaming, or wellness, is that they’re easy to forget if you don’t build a habit around them. The issuers count on that. The credit doesn’t roll over, and there’s no reminder nudging you to use it before the month ends.
Studies of the best credit cards for dining found that Chase Sapphire and American Express offered some of the greatest cardholder benefits, including triple points on dining and 60,000 bonus points after meeting a spending threshold in the first few months. The points accumulate fine. It’s the non-points credits that get lost.
The Income Gap in Rewards Redemption
About one-third of households earning less than $50,000 per year left rewards unused in the past year. This matters because these cardholders arguably stand to benefit the most from getting every dollar’s worth out of their cards.
About 71% of Americans report having a rewards, points, or cash-back credit card, and 70% of cardholders say cash back is the perk they value most. Valuing a perk and actually redeeming it are two different behaviors, and the gap between them is where money disappears.
Among younger cardholders, 41% of Gen Z and 40% of Millennials cite rewards as a major factor in card usage decisions, yet only 16% of Gen Z redeem points immediately, and over 10% say they don’t redeem at all. Awareness of rewards doesn’t automatically translate to action.
Why Issuers Don’t Make It Easy
The CFPB has issued warnings to issuers to avoid devaluing rewards through hidden terms, and has warned that revoking or devaluing rewards may breach consumer law protections. That regulatory pressure signals just how opaque the system has become.
Some major card issuers have raised redemption thresholds or tightened terms due to cost pressures, and regulatory scrutiny has led a majority of issuers to update their transparency around restrictions and bonus conditions. The fine print changes more often than most cardholders realize.
The CFPB notes that rewards figures often don’t include the value of non-cash perks like airport lounge access, free checked bags, and insurance coverage. Cardholders with the highest credit scores actually earned rewards at a lower cash rate than others, which the bureau speculates may be because they gravitate toward cards with non-cash perks instead. Those perks only pay off if you know to claim them.
What Actually Gets Redeemed, and What Doesn’t
Among cardholders who redeemed rewards in the past year, 71% redeemed cash back, 21% redeemed points or gift cards, 12% earned a free flight, and 12% earned a free hotel stay. Cash back dominates because it’s the simplest option. Everything else requires a bit more effort.
More than three-quarters of American consumers said they redeemed travel rewards within a year after earning them, though free hotel stays and flights remain less popular redemption choices than cash back and gift cards. Convenience consistently beats value in consumer behavior.
Holders of general purpose credit cards earned a collective $47.5 billion in rewards in 2024, according to the CFPB. That’s the earning side. The spending side, including the insurance, travel protection, and monthly credits that require no points at all, remains deeply underused across virtually every demographic.
The Takeaway
The most overlooked credit card perk isn’t any single feature. It’s the entire category of built-in protections and credits that require zero points and zero extra spending to access. They exist the moment you’re approved. They just need you to know they’re there.
Spending ten minutes reading your card’s benefits guide, or even searching your card name alongside words like “insurance” or “credit,” is often all it takes to find real value that’s already yours. With the average annual fee on a consumer credit card sitting at $127 in 2024, getting your full money’s worth means looking beyond the rewards rate and into the full benefits package.
The perk sitting unused in your wallet isn’t mysterious. It’s just unread. That’s a fixable problem.
AI Disclaimer: This article was created with the assistance of AI tools and reviewed by a human editor.