Grief scrambles the brain in ways that are hard to explain until you’ve lived through it. The paperwork arrives. The phone calls start. And somewhere in the middle of all that, major financial decisions demand your attention, often before you feel even remotely ready. The first year after losing a spouse is one of the most financially vulnerable periods a person can face, not because people are careless, but because loss simply makes clear thinking harder.
The stakes are real. Household income for widows declines an average of thirty-seven percent when their spouse dies, while widowers lose an average of twenty-two percent. According to a 2024 Thrivent survey, roughly four in ten widows say they had not engaged in any financial planning before their spouse’s death. These numbers make the mistakes below not just common but predictable, and knowing about them in advance is a meaningful form of protection.
Mistake 1: Making Major Financial Decisions Too Soon
The pressure to act quickly can feel overwhelming. Accounts need sorting, real estate decisions loom, and well-meaning family members often push for faster resolutions than are truly necessary. Grief impairs decision-making in concrete ways: the stress and disorientation of loss affects concentration, risk perception, and the ability to evaluate long-term consequences, which is exactly why financial planners who specialize in working with widowed clients strongly advise against making major irreversible financial decisions in the first six to twelve months.
Acting too fast on major financial decisions like selling the family home, restructuring investments, or making large gifts to family members is one of the most common and consequential mistakes. Financial planning professionals broadly recommend waiting a year before making any significant, irreversible moves, because grief affects judgment in ways that aren’t always obvious in the moment.
Experts note that widows might sell the family house for less than it’s worth just to get rid of it, or invest IRA assets in annuities to guarantee income, even though the IRA is already tax-advantaged and the annuity might not pay out enough for minimum-required distributions. Patience, in the first year especially, is not procrastination. It’s strategy.
Mistake 2: Overspending as Emotional Relief
Too often in that first year, surviving spouses expend large sums of money to purchase vehicles, improve their home, or take extended and numerous trips. This is completely understandable. A change of scenery, a renovation project, a new car, these feel like ways to move forward, to reclaim some sense of control. The problem is that emotional spending rarely stops at one purchase.
Grief experts and financial advisors alike note that a surviving spouse’s capacity to reason and think clearly is impaired during this period. The money feels more abstract at first, especially if the deceased handled most of the financial management. If your husband or wife was the one who paid the bills and made the financial decisions, you may find it empowering to be in control of the purse strings, but you may not have as much money as you think.
Mistake 3: Ignoring the Tax Bracket Shift
Few things catch newly widowed people off guard quite like the tax bill that arrives in the following year. A married couple filing jointly with seventy-five thousand dollars in taxable income falls into the twelve percent federal tax bracket, while a single filer with the same income lands in the twenty-two percent bracket. That is not a small difference. It represents a meaningful reduction in take-home income that many people simply don’t anticipate.
Adding to the tax burden, the standard deduction gets cut in half. Married couples filing jointly receive a standard deduction of thirty thousand dollars in 2025, while single filers receive just fifteen thousand dollars. Once a surviving spouse loses access to joint filing status, many experience what is sometimes called the “widow’s tax penalty,” a meaningful jump in effective tax rate because the single filer brackets are much narrower, which can also affect Medicare premium surcharges and the taxation of Social Security benefits.
Working with a tax professional in the first year, not just during filing season, can help a surviving spouse understand and plan for this shift before it arrives as an unwelcome surprise.
Mistake 4: Missing Out on Social Security Benefits
Social Security survivor benefits are one of the most significant financial resources available to widowed Americans, and they are also among the most commonly misunderstood or simply overlooked. Retirees must learn to live on one Social Security check instead of two, though a surviving spouse may qualify for a higher survivor benefit equal to one hundred percent of their deceased spouse’s benefit. Nearly six million widows and widowers currently receive Social Security survivor benefits, according to AARP.
The survivor payment is unlikely to fully replace previous household income, especially if both spouses were receiving benefits. Claiming survivor benefits before reaching Social Security’s full retirement age of sixty-seven for those born in 1960 or later results in a permanently reduced monthly benefit. The timing of when to claim, and which benefit to claim first, is a decision worth discussing with a financial advisor who understands Social Security strategy specifically. Getting it wrong can mean leaving real money on the table for years.
Mistake 5: Falling Victim to Financial Scams
Grief makes people vulnerable. Scammers know this, and they actively target people who have recently lost a spouse. In 2025, online scams cost American seniors nearly 7.75 billion dollars across more than 201,000 reported victims aged sixty and older, with an average loss per victim of roughly thirty-eight thousand, five hundred dollars. These are not abstract figures. Each one represents a real person who was targeted during a difficult time in their life.
Investment fraud is the most financially damaging form of elder fraud, averaging losses of nearly two hundred thousand dollars per victim. According to Incogni’s analysis of FBI data, roughly seventy-two percent of elder fraud cases in 2024 were enabled by victims’ personal data being exposed online. The first year after a loss is particularly risky because it’s easy to fall prey to scams, especially if much of the couple’s financial planning was handled by the deceased spouse.
Mistake 6: Not Knowing Where the Money Is
In many households, one partner manages the finances and the other is largely uninvolved. When the financial manager dies first, the surviving spouse can find themselves completely in the dark about accounts, debts, automatic payments, and income sources. A recent national survey of widowed women found that forty-one percent reported having little to no prior financial conversations with their spouse, and only about half said they felt prepared to manage their finances after their spouse’s passing.
Surviving spouses may lose access to credit cards they thought were theirs but were established under their spouse’s name, and access to savings, retirement accounts, and investments could be delayed or blocked if beneficiary information was not properly filled out. Locating all accounts, income sources, and legal documents as early as possible in the process is one of the most practical steps a surviving spouse can take.
Mistake 7: Giving Too Much Money Away to Family
The impulse to help children or grandchildren financially, especially right after a loss, is deeply human. Whether it’s contributing to a down payment, covering moving costs, or simply feeling the need to provide, many surviving spouses give generously in the first year, sometimes more than they can afford. Financial advisors are struck by cases where widows gave thousands of dollars to their children for car down payments and apartment moves, but should not have parted with so much money given their own financial situation.
The concern is not generosity itself but timing. Housing costs, healthcare, and living expenses continue even as income sources change, and data shows that surviving spouses are more likely to face housing cost pressures than their peers, with about thirty-five percent of widowed homeowners spending at least thirty percent of their income on housing, compared with twenty-two percent of older homeowners overall. Rebuilding financial stability for yourself first is not selfishness. It is sound planning.
Mistake 8: Neglecting to Update Beneficiary Designations and Estate Documents
After a spouse dies, the surviving partner often inherits accounts, property, and assets, but their own estate documents remain unchanged. This means retirement accounts, life insurance policies, and investment accounts may still list the deceased spouse as beneficiary, or list no one at all. The legal and financial consequences of this oversight can be significant, particularly for children or other heirs down the line.
Inherited IRAs carry required minimum distribution rules that differ from accounts owned outright, and missing those distributions triggers IRS penalties. Account titling, online credentials, and automatic payments are easy to overlook and can become problems quickly if they lapse. Taking inventory of every account and document, and updating them with the help of an estate attorney, is one of those tasks that feels easy to defer but carries real risk if ignored.
Mistake 9: Underestimating the Drop in Credit Score
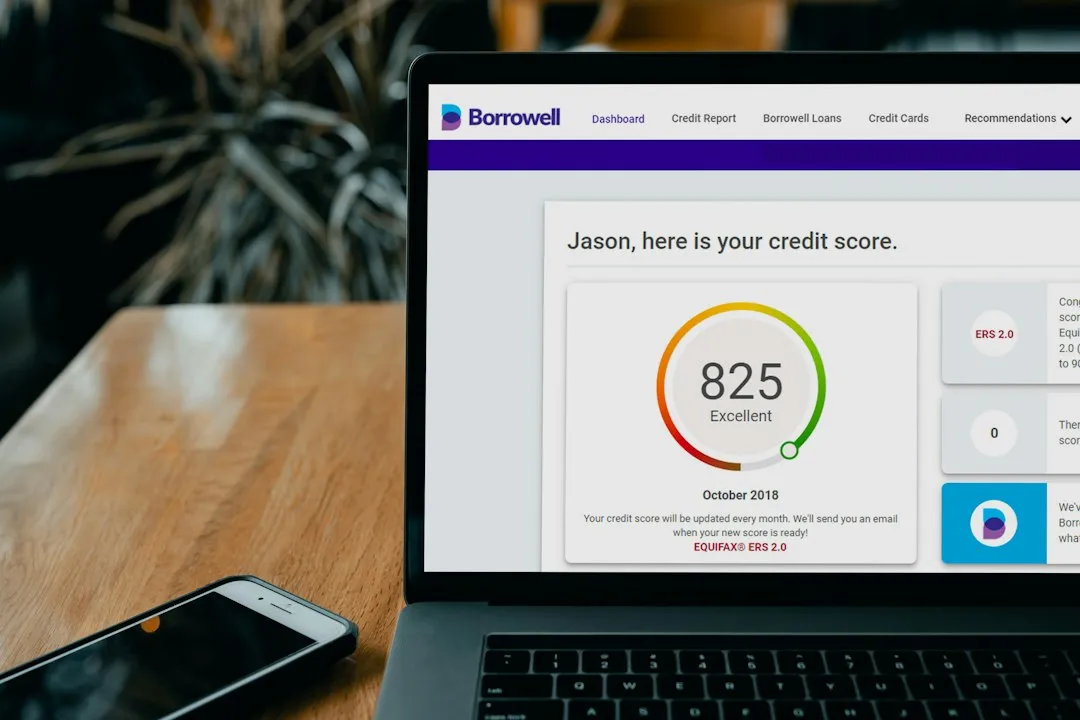
Most people don’t expect their credit score to take a hit after losing a spouse, but the data shows it often does. Surviving spouses experience an average ten-point decline in their credit score following their partner’s death, according to research. This happens for a range of reasons, including the closure of joint accounts, changes in credit utilization ratios, and missed payments during the chaos of the first few months.
A surviving spouse may also lose access to credit cards they thought were theirs but that were established under their spouse’s name. This can leave someone suddenly without access to credit at exactly the moment they may need it most. Monitoring your credit early, opening accounts in your own name if needed, and staying on top of automatic payments can prevent a temporary disruption from becoming a longer-term problem.
Mistake 10: Going It Alone Without Professional Guidance
Research shows that grief over the sudden death of a partner leads one in six surviving partners to experience severe enough psychological distress that they begin taking sedatives or antidepressants, and if the death also results in a noticeable loss of income, the share of widows and widowers using psychotropic medication is significantly higher, reflecting how economic insecurity greatly amplifies the mental strain after losing a loved one. Managing complex financial decisions under those conditions, without any professional support, is simply asking too much of yourself.
The financial impact of losing a spouse is real and often underestimated, with rates of financial insolvency doubling in widowed households compared to their married counterparts. A Thrivent survey found that more than half of widowed women experienced financial challenges, with fifty-one percent living paycheck to paycheck or struggling to manage their bills. A fiduciary financial advisor, ideally one who specializes in working with widowed clients, can bring both technical knowledge and a steadying perspective at one of the most financially complex moments of a person’s life.
The Takeaway
The financial mistakes made in the first year after losing a spouse are rarely the result of ignorance or recklessness. They come from grief, from exhaustion, from suddenly having to manage a whole financial life that may have previously been shared or handled by someone else. Understanding these pitfalls before or during that period doesn’t make the year easier emotionally, but it can meaningfully reduce the financial damage that follows.
Give yourself permission to move slowly where you can. Lean on professionals who genuinely specialize in this area. The decisions that feel urgent in month two often look very different in month fourteen. Protecting your financial future is not a betrayal of the grief you’re carrying. It’s the most responsible thing you can do for yourself, and for everyone who depends on you.
AI Disclaimer: This article was created with the assistance of AI tools and reviewed by a human editor.