
1. Selling the Family Home Too Quickly
Rushing the sale of a long-held family home is perhaps the single most cited source of early regret among retirees. People often end up downsizing too quickly and later regretting their decision, and it’s especially easy to regret letting go of your family home too soon. The emotional weight of a home built over thirty or forty years tends to hit harder than people expect once the keys are handed over.
Retirees often regret not having room for family gatherings or for friends and family to stay with them once they’ve moved somewhere smaller. That loss of hosting capacity can feel abstract on paper and very real during the first holiday season in a compact apartment or condo. The family visit that used to fill a house now strains a two-bedroom unit.
A couple finding themselves homesick, with grandchildren visiting less often due to the lack of space, and deeply regretting not being able to host family gatherings like they used to, is a story that repeats itself across the country. Taking time, even an extra six months, before listing the property can make a meaningful difference in whether the decision feels right long-term.
2. Underestimating the True Cost of the Move
One of the biggest mistakes is assuming a smaller home will automatically be cheaper. Many retirees underestimate taxes, HOA fees, closing costs, repairs, and moving expenses. The word “smaller” suggests savings, but the math rarely works out as cleanly as imagined.
The moving process itself can be pricey. Homeowners association fees, getting your house market-ready, homeowners insurance, property taxes, real estate agent fees, and purchasing new furniture for your space are just a few expenses that can add up during a move. Many retirees budget for the purchase price of the new home without accounting for the full transition cost.
Many retirees end up spending more than expected because they focus on selling the old house and not on the full cost of the move, the replacement home, and the lifestyle trade-offs that come after it. Repairs, staging, commissions, moving services, storage, legal costs, and the price of the next property can still eat into proceeds. Running a detailed, line-item budget before signing anything is not optional. It is essential.
3. Moving Away From Their Community
One of the quieter regrets is geographic. Chasing lower costs or warmer weather sometimes means leaving behind the neighborhood, friends, doctors, and routines that made daily life feel meaningful. Retirees may regret downsizing their homes, personal possessions, and social commitments due to emotional impacts and loss of community ties.
Retirees often focus on the property and not enough on the area around it. A beautiful downsized home can still be a poor fit if it leaves you far from the people and places that anchor your daily life. Proximity to friends, family, and familiar healthcare providers is worth far more than it looks on a spreadsheet.
Older adults can face struggles that involve reduced contact with family and old friends, as well as difficulty forming new friendships and connections, and research published in the journal Psychology and Aging found that older adults may face double jeopardy when relocating, as they are vulnerable to both age-related and migration-related risk factors for loneliness. That loneliness is not just emotional. It carries measurable health consequences.
4. Ignoring the Health Risks of Social Isolation
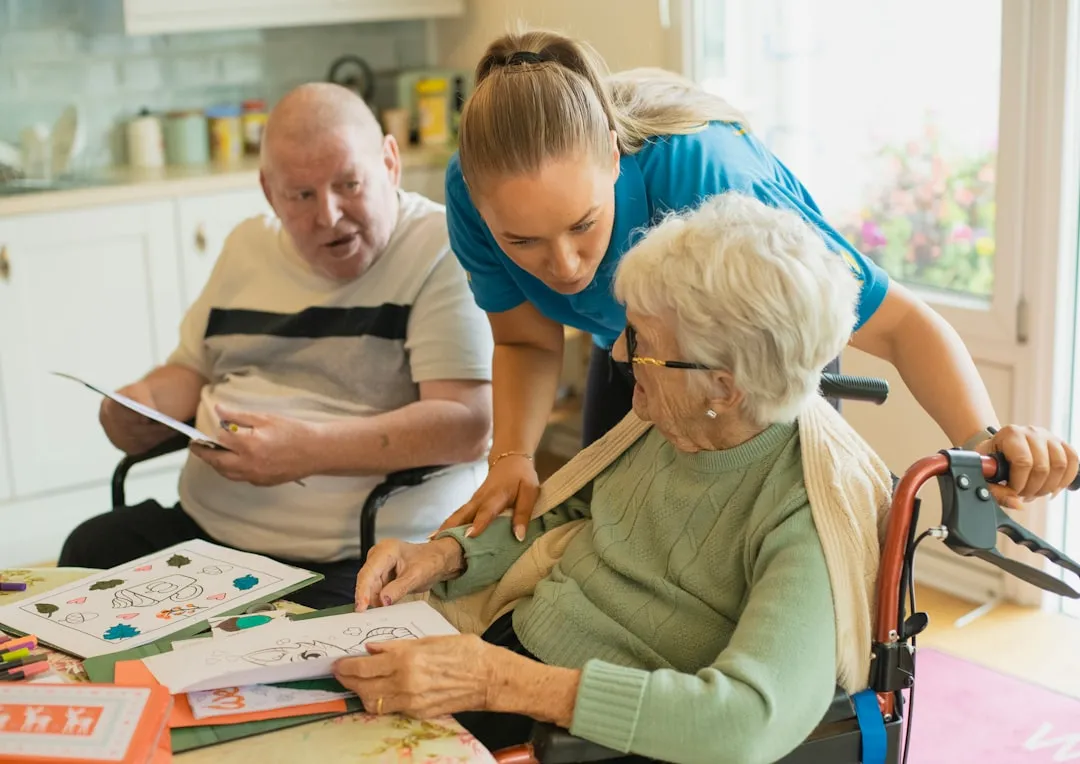
Moving to a new city or a retirement-focused community can feel exciting at first. Within a few months, however, many retirees find that building new social networks in their sixties and seventies is harder than it was at thirty. The effects of social isolation on mental health include elevated rates of anxiety, depression, and cognitive decline, and studies link social isolation and depression to a roughly forty percent increased risk of developing dementia.
Social isolation can lead to increased anxiety levels, making it difficult for individuals to engage with the world around them. It also extends to physical health, with isolated seniors at higher risk for chronic conditions like hypertension and heart disease, and the lack of social interaction can lead to a more sedentary lifestyle, further exacerbating health issues.
Financial planners and advisors have noted the regret in clients who downsize their social circles and commitments too drastically. This is rarely something people plan for. Most of the focus goes toward the financial side of the move, not the social architecture of a new life. Mapping out where regular social contact will come from before relocating is a step most people skip, to their detriment.
5. Getting Rid of Too Many Possessions
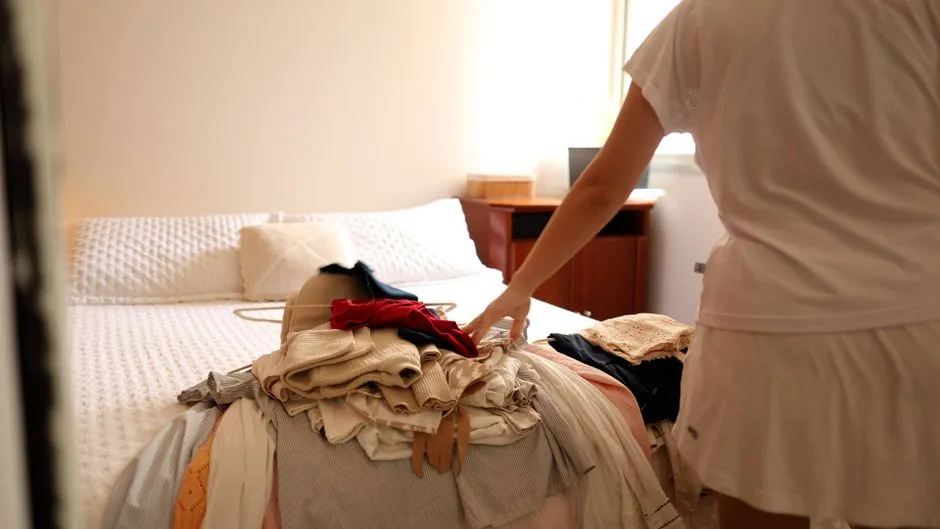
Decluttering before a move feels productive, even liberating. The regret often follows months later, when a retiree realizes a cherished piece of furniture, a set of family heirlooms, or a collection built over decades is simply gone. A lot of retirees will get rid of sentimental items such as family heirlooms or other meaningful belongings to declutter, and getting rid of too much can lead to regret, especially if the decision was made primarily based on finances.
Downsizing with only finances in mind can have a major impact on emotional well-being, especially if it means selling, donating, or throwing out the things that bring nonmonetary value to your life. Those objects carry identity. Losing them can feel, in a quiet way, like losing a part of yourself.
Many clients feel sad and often angry because the items had taken them a while to save up to purchase. Finding out that solid wood furniture bought for thousands of dollars sells online for maybe fifty dollars hurts pride and leaves people feeling disrespected. A better approach is to move more slowly, store items temporarily, and make final decisions after living in the new space for a few months.
6. Choosing the Wrong Location for Future Health Needs
A neighborhood that works perfectly at sixty-five may not work at seventy-five. Many retirees choose their downsized home based on how they feel right now, not on where they might need to be in ten years. Some people put off downsizing until a health issue or family emergency forces a rushed move, which can leave them selling under pressure, accepting lower offers, or moving before they have time to compare neighborhoods, tax rates, and healthcare access.
Access to quality healthcare, specialist clinics, and familiar physicians is something easy to take for granted until it’s gone. Retirees who relocate to scenic but remote areas sometimes discover that routine medical appointments now require long drives or even overnight stays. That inconvenience compounds quickly with age.
According to the CareScout Cost of Care Survey, the median annual cost of living in an assisted living community or a semi-private room in a nursing home could be $74,400 and $114,975, respectively. Choosing a location without considering proximity to this kind of care, should it become necessary, can create a very expensive problem later.
7. Dropping Long-Term Care Insurance to Cut Costs
When retirees look for places to trim their monthly expenses, insurance premiums are a tempting target. Long-term care insurance in particular can feel like an abstract cost, especially when someone feels healthy and active. This oversight can cost you. According to the CareScout Cost of Care Survey, the median annual cost of assisted living or a nursing home semi-private room could reach $74,400 and $114,975, respectively.
The logic of cutting a premium to save a few hundred dollars a month sounds reasonable until it isn’t. Without adequate coverage, a single extended health event can consume years of carefully managed savings far faster than most retirees anticipate. Downsizing health insurance to save money could backfire, especially as health concerns grow with age. Opting for lower premiums now could lead to regret when faced with high medical costs later.
This mistake is especially relevant for retirees who step down from more comprehensive employer-sponsored plans during the transition period. The gap between early retirement and Medicare eligibility at sixty-five can be financially dangerous if coverage is reduced too aggressively in the name of cutting costs.
8. Underestimating the Emotional Impact of the Transition
The practical side of downsizing gets most of the attention. The emotional side tends to get discovered the hard way. Leaving the home where children were raised, holidays were celebrated, and ordinary life unfolded over decades is a significant loss, even when the move is clearly the right financial decision. Letting emotions drive the decision can lead to hasty choices, and emotion-driven decisions often result in regret or the realization that the new place doesn’t truly meet their needs.
Downsizing with only finances in mind can have a major impact on emotional well-being, especially if it means letting go of things that bring nonmonetary value to life. Grief about leaving a home is real and valid, even if it surprises people who expected to feel only relief.
Giving yourself permission to grieve the old space while building genuine enthusiasm for the new one takes time. Retirees who acknowledge the emotional complexity of the move tend to adjust better. Those who dismiss it as irrational often find it surfaces anyway, in ways that are harder to manage months into the new chapter.
9. Failing to Plan for Loss of Independence
Moving from a standalone home with a yard, a garage, and personal space to a smaller apartment or an age-restricted community involves trade-offs that aren’t always obvious until after the move. Someone who owns their own home with a yard and some space between themselves and their neighbors, who moves into a much smaller place or a 55-or-older retirement community, loses some of the privacy and space they once had, and this could be a stressful or frustrating experience.
The biggest regret senior wealth advisors hear about from clients who downsize is the lack of space. This can pop up in several ways: lack of personal space and privacy within the home, lack of space for hobbies and personal projects, and loss of functionality, such as going from a separate home office to a room that doubles as a spare bedroom, storage room, and craft room.
The loss of outdoor space hits especially hard for retirees who gardened, kept a workshop, or simply valued a private backyard for morning coffee. Many apartments and smaller homes don’t have the space for a private yard or a garden, and losing that space can be something retirees end up regretting later. Testing a new lifestyle, through an extended rental before buying, can reveal these friction points before they become permanent ones.
10. Moving Too Far From Family
The retirement destination that looks perfect in a brochure can feel isolating once the novelty fades and grandchildren remain several states away. Distance from family is one of the most emotionally consequential choices retirees make, and it’s also one of the hardest to reverse once the old home is sold. Downsizing isn’t always a bad idea, but proximity to family is perhaps the most legitimate nonfinancial factor to weigh when choosing where to land.
Many older Americans and retirees are rethinking relocation because, for many people, letting go of their homes and moving far away simply doesn’t make financial or personal sense. The appeal of low-cost sunbelt living or coastal scenery often competes quietly with the reality that meaningful relationships require proximity.
Research is consistently clear that strong family and social ties are among the most important predictors of health and happiness in older adults. Isolation doesn’t just feel bad. It’s linked to anxiety, depression, heart disease, cognitive decline, and higher healthcare costs. Older adults have been found to spend the most time alone of any age group, and this can lead to greater health risks. Before choosing a retirement address based primarily on climate or cost of living, it pays to ask honestly: how often will the people who matter most actually show up there?
A Few Things Worth Remembering
Downsizing is not inherently a mistake. For many retirees it genuinely simplifies life, frees up capital, and reduces the burden of home maintenance. The problems arise when the decision is rushed, financially misunderstood, or stripped of its emotional complexity. With retirement comes the need, practical, financial, or otherwise, for downsizing, but oftentimes people end up downsizing either too quickly or too much and later regretting their decision.
The clearest pattern across all of these mistakes is speed. Retirees who give themselves adequate time to plan, test new living arrangements before committing, and account for both the financial and personal costs of the move tend to report far fewer regrets. Before cutting, it helps to ask what each decision is really doing for your life. Some of those things are working harder than the spreadsheet shows.
Ultimately, the first year after a major downsizing move is when reality meets expectation. Getting the decision right takes more than a number-crunching session. It takes an honest conversation with yourself about how you actually want to live, and with whom.
AI Disclaimer: This article was created with the assistance of AI tools and reviewed by a human editor.